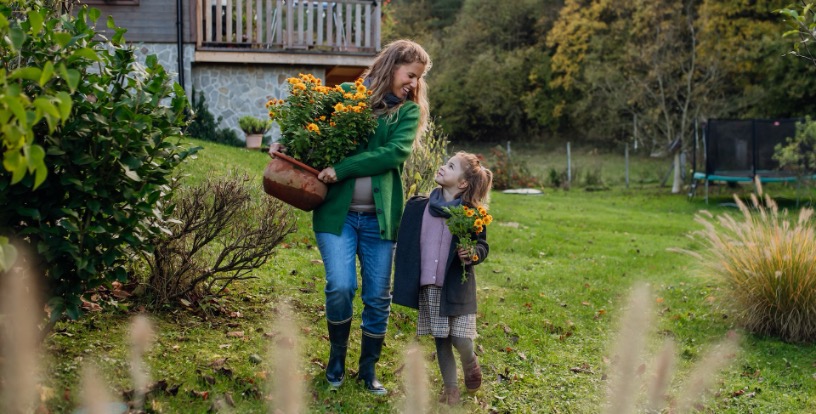
Success is important, but some of life's greatest returns – memories – never appear on financial statements and can't be measured by numbers alone.
When ROI stops telling the whole story
One of the metrics widely used in the financial profession to evaluate a decision is Return on Investment (ROI). It’s also used in other areas, such as marketing and operational planning meetings for larger companies and corporations.
This metric drives us to optimise portfolios to chase the highest possible yield. We scrutinise management fees, track our compound interest and celebrate when the graph moves up and to the right. In the world of wealth accumulation, ROI is widely considered the ultimate benchmark of success.
But a problem arises when we apply this rigid, mathematical framework to our personal lives.
If you view your life strictly through the lens of financial ROI, spending money on a family holiday, an extended sabbatical, or a celebratory dinner can easily be seen as a loss. It’s capital leaving the balance sheet that’ll never financially compound. But true lifestyle financial planning requires us to look beyond the numbers and embrace a different, far more valuable metric: the Return on Memories (ROM).
The return that keeps paying
When you invest capital in a meaningful experience, the financial transaction is only the beginning.
Think about a brilliant family trip you took five years ago. You paid for the transport, meals and the accommodation once, but how many times have you told a story from that trip? How many times have you laughed about a shared mishap or looked back at the photos and videos with a profound sense of gratitude?
That is ROM in action. Experiences pay out a psychological and emotional dividend that compounds over the rest of your life. You get to relive the joy of that investment again and again, long after the money was spent. And it may not show up on your statement.
A strong financial plan should therefore create room for both security and experience. The goal is not to choose between future stability and present joy, but to recognise that money can serve both when those priorities are considered deliberately, together and in advance.
Some opportunities have an expiry date
Unlike financial investments, which generally get better the longer you wait, investments in memories often have a strict expiry date.
There’s a brief, magical window of time when your children actually want to go on holiday with you. There’s a specific season when your parents are still mobile enough to navigate a foreign city. There’s a window right now where you have the health and the energy to tackle a bucket-list adventure.
If you delay these experiences in the name of maximising your financial ROI, the window closes. You might have more money in the bank a decade from now, but you’ll have permanently missed the opportunity to fund that specific memory.
Spend with intention
This isn’t a licence to be reckless with your capital or an excuse to abandon your budget. It’s a reminder to be deeply intentional.
Your money is a tool. Its primary purpose is not to simply sit on a spreadsheet and multiply until the day you die – its purpose is to fund a purposeful life. Once your future is secure and your financial boundaries are respected, you must allow yourself to spend your money on what actually matters.
The returns that matter most
When you reach the end of the road, you won’t look back and fondly reminisce about the year your portfolio beat the market by 2%. You’ll look back at the highlight reel of your life: the people, the places and the shared experiences.
Make sure you’re allocating enough capital to fund the memories that matter most.
Next up: Talking to your family about money