The financial price of waiting for ‘someday’ can be higher than you realise.
Financial goals are important, but if you're constantly postponing life until 'someday', you may be paying a higher price than you realise.
Financial planning should help you build for tomorrow without sacrificing the experiences, health and relationships that matter today.
The financial price of the deferred life
There’s a very common narrative that high achievers tend to buy into. It’s the idea of the deferred life.
We work relentlessly in our thirties, forties and fifties, pouring all our surplus time and energy into building our careers and our portfolios. We tell ourselves we’re making sacrifices now so we can finally relax, travel and enjoy our lives ‘someday’ when we cross a specific financial finish line.
But this mindset contains a hidden, incredibly dangerous flaw. It assumes that when ‘someday’ finally arrives, we’ll still have the physical capacity to enjoy it.
The financial price of that assumption is easy to overlook because it cannot always be measured on a balance sheet. Time, energy and physical capacity have value too, and unlike money, they cannot simply be earned back later.
Financial capital versus physical capital
When we plan for the future, we can easily become obsessed with our financial capital. We track compound interest, monitor yields and ensure the portfolio is perfectly balanced. But we risk ignoring our physical capital.
Your physical capital can be described as your health, mobility and energy levels. And unlike a well-managed investment portfolio, your physical capital doesn’t compound over time – it naturally depreciates.
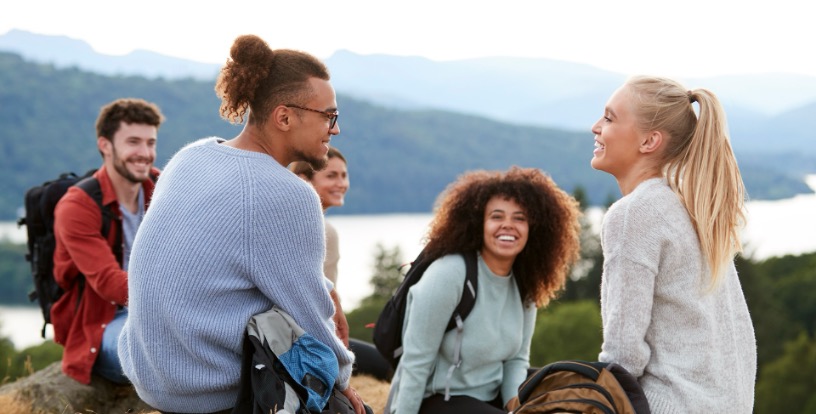
It’s easy to dream about spending your retirement tackling multi-day hiking trails, camping out under the stars, or finally having the time to master those mountain bike routes. But if you spend three decades sitting behind a desk, sacrificing your sleep and ignoring your health in the pursuit of a larger bank balance, those dreams might remain entirely out of reach.
A fully funded pension can’t buy back worn-out knees or a depleted cardiovascular system.
The three phases of later life
In financial planning, we often talk about the three distinct phases of later life:
1. The go-go years: The early years of retirement when you have both the time and the physical health to travel, explore and engage in high-energy activities.
2. The slow-go years: The phase where you’re still healthy but naturally begin to slow down. Long-haul flights and strenuous hikes are replaced by gentler pursuits closer to home.
3. The no-go years: The later years where health issues and limited mobility dictate your lifestyle and your world naturally becomes smaller.
The tragedy of the deferred life is that many people risk delaying their biggest, most physically demanding dreams until they reach their mid-sixties, only to discover that their ‘go-go years’ may already be behind them.
The financial price of missed opportunities
The financial price of waiting for someday is not always visible in rands and cents. It can be measured in missed seasons, declining energy and experiences that become harder to pursue with time. Financial planning should therefore make room for opportunities whose value depends on when they happen, not only whether you can afford them. Sometimes the wisest use of money is to protect the version of life available to you right now.
Some opportunities are valuable precisely because of when they happen. A family adventure while your children still want to travel with you, a challenging hike while your body allows it, or simply taking time away while you have the energy to enjoy it may not offer the same return if postponed indefinitely.
A plan that permits you to live today
A truly successful financial plan doesn’t just prepare you for the future – it permits you to live today.
It’s about finding the delicate balance between saving for tomorrow and experiencing the present. If your financial plan is so rigid that it prevents you from taking a long weekend to recharge, investing in your physical health, or enjoying an active holiday while your body is at its peak, it may be time to rewrite it.
Avoiding the financial price of ‘someday’ does not mean abandoning discipline or compromising your future. It means recognising that a good financial plan should make deliberate room for both future security and the experiences that are uniquely available to you today.
Protecting your primary wealth
Don’t arrive at your financial finish line with a full bank account and an empty tank. Treat your physical health with the same strategic reverence you give your investment portfolio, because your health is – and always will be – your primary wealth.
The financial price of ‘someday’ becomes greatest when the life you worked so hard to fund is no longer fully available to you.
Next: The Rule of 72: Compounding
Have you read Redefining true financial well-being yet?