A financial plan is only as strong as the base camp that protects it from life's inevitable disruptions.
Protecting what supports the summit
When we sit down to build a financial plan, our eyes are naturally drawn to the summit, not the base camp. We focus our energy on big, inspiring goals: retiring with dignity, leaving a meaningful legacy, experiencing financial independence or funding our children’s education.
We engineer our long-term investments to weather global economic storms and compound beautifully over decades.
But in our rush to conquer the mountain, we often forget to protect the base camp.
The disruption of everyday setbacks
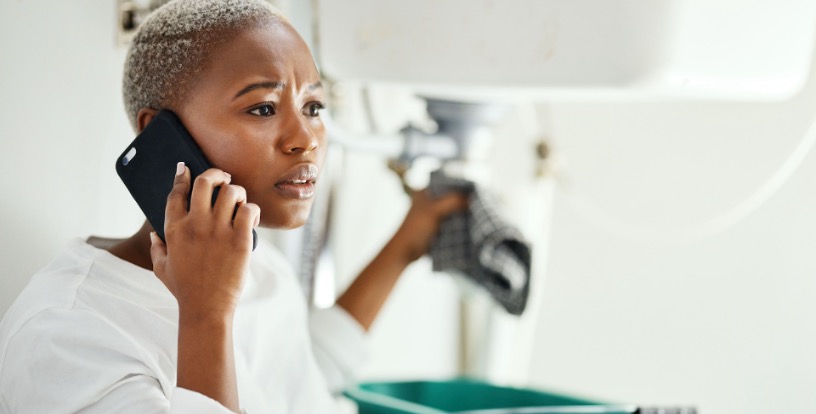
A burst geyser flooding the hallway, a stolen bicycle, or a minor car accident on the morning school run is rarely an event that’ll cause total financial ruin. But it’s a massive disruption. It steals your time, drains your energy and completely hijacks your emotional bandwidth.
Traditionally, short-term insurance (covering your home, car and everyday valuables) is viewed as the ultimate ‘grudge purchase’. It’s a line item in the monthly budget we pay with a sigh, hoping we’ll never have to use it.
Because we view it as an annoyance, we tend to shop for the absolute lowest premium, entirely ignoring the quality of the cover or the efficiency of the claims process until disaster strikes.
Reframing what you’re really buying
This is a flawed way to think about a financial plan because it ignores the systems designed to protect it. We need to reframe what you’re actually buying.
When you secure high-quality short-term cover, you're strengthening the base camp of your financial plan, not just buying a replacement laptop or a hired car. You’re buying a perimeter fence for your peace of mind.
When a pipe bursts at 6:00 am on a Tuesday, do you want to spend your morning frantically scrolling for a reliable plumber or arguing with a call centre? Or would you prefer to make a single phone call, have the problem quickly resolved by trusted professionals and get back to your life?
Short-term cover allows you to choose how scenarios like this will play out and impact your daily life.
The strongest plans are not built only for ideal conditions. They are designed to absorb ordinary shocks without forcing every unexpected expense to become an emergency or a threat to the goals you value most.
Protecting your long-term capital
There’s another highly strategic reason for a robust short-term cover plan.
If you don't have adequate insurance in place, life's bumps can undermine your financial plan by forcing you to become your own insurer. When an accident happens, you have to dig into your hard-earned cash reserves, or worse, liquidate long-term investments at exactly the wrong time.
When you dip into your core wealth to pay for a short-term accident, you interrupt the compounding engine that sits at the heart of your financial plan. You allow a minor, everyday inconvenience to disrupt not only your day, but a carefully engineered, multi-decade strategy.
Keeping your focus on the summit
Your wealth is supposed to serve you, not the other way around.
Take a moment to review the base camp of your financial plan by assessing whether your short-term cover provides the protection you need. Stop viewing it as a grudge purchase and start viewing it as a strategic boundary. It’s the moat that protects your long-term capital, ensuring that when life's inevitable accidents happen, your focus remains exactly where it should be: on the summit, not the storm.
Have you read How strong is your financial plan? Yet?
Or dive into our next article: Memories won’t show up on your financial statements